How Semaglutide Redefined Canadian Health, Wealth, and Waistlines
Cultural and economic explosion of GLP-1 weight-loss drugs in Canada, breaking down the corporate forces of Novo Nordisk and Eli Lilly
3 min read · Toronto, Canada
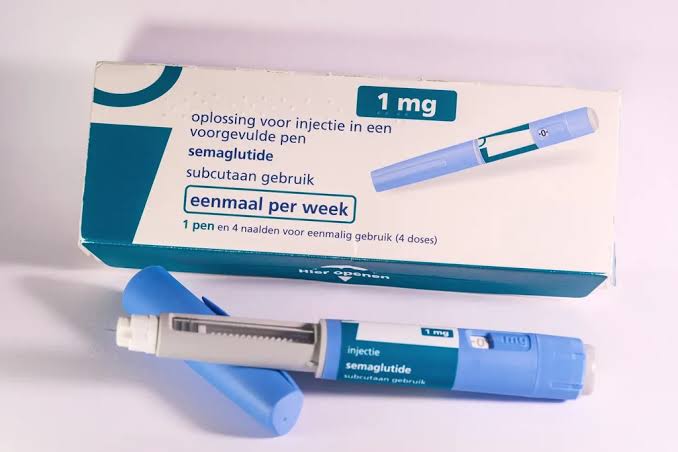
Few pharmacological products in modern history have crossed the threshold from specialized endocrinology to mainstream cultural fixation quite like the class of GLP-1 receptor agonists. In Canada, where roughly three million adults are estimated to be utilizing or actively seeking these metabolic disruptors, the narrative is no longer solely about diabetes management or chronic weight control. It is an economic, political, and social phenomenon.
At the epicenter of this surge is semaglutide—marketed globally under brand names like Ozempic (approved for Type 2 diabetes) and Wegovy (specifically approved for chronic weight management). Alongside competing molecules like tirzepatide (Mounjaro), these weekly subcutaneous injections have re-engineered lifestyle habits, shifted consumer spending toward fresh produce and lean proteins, and put unprecedented pressure on provincial healthcare supply chains.
The Corporate Powerhouses Behind the Movement
The commercial engine driving this revolution is anchored by global pharmaceutical giants that have captured staggering market capitalization on the back of these compounds:
Novo Nordisk (The Pioneer): The Danish multinational pharmaceutical giant is the foundational force behind the craze. By developing semaglutide, Novo Nordisk captured an overwhelming majority stake in Canada’s GLP-1 market. Their strategic push successfully marketed the same core molecule across different dosage thresholds for distinct clinical indications—Ozempic for glycemic control and Wegovy for obesity.
Eli Lilly (The Challenger): As the primary competitor, the U.S.-based pharmaceutical titan entered the ring with tirzepatide (Mounjaro/Zepbound), offering a dual-action mechanism (targeting both GLP-1 and GIP receptors) that clinical trials show yields even higher percentage weight loss.
Domestic Generic Manufacturers: Breaking a long corporate monopoly, Canadian regulators made history when Health Canada approved the world’s first generic semaglutide options (led by submissions from firms like Apotex), signaling an impending shift toward lower consumer acquisition costs as patents face pressure.
Advantages and Disadvantages: The Clinical Balance Sheet
The Advantages
Significant Metabolic Reset: Clinical trials demonstrate that chronic weight management formulations like Wegovy help patients achieve sustained body weight reductions averaging roughly 15% over extended treatment windows.
Cardiovascular Protection: Beyond weight loss, large-scale clinical data (such as the landmark SELECT trial) revealed that semaglutide reduces major adverse cardiovascular events—such as stroke and heart attack—by up to 20% in high-risk patients.
Systemic Health Improvements: Real-world tracking shows measurable improvements in secondary comorbidities, including lowered blood pressure, improved glycemic metrics, and reduced systemic inflammation.
The Disadvantages
The Gastrointestinal Toll: Common side effects include persistent nausea, severe acid reflux, gastroparesis (stomach paralysis), vomiting, and episodic fatigue, particularly during dosage titration phases.
The Permanence Trap: Clinical data indicates that discontinuing the medication frequently results in a rapid rebound of both body weight and systemic metabolic markers, suggesting lifelong maintenance may be required for sustained efficacy.
Cost and Out-of-Pocket Burden: With monthly expenditures running into hundreds of dollars for uninsured or partially covered patients, access remains deeply stratified along socioeconomic lines.
Popularity and Market Growth Trajectory
The steep upward trajectory of GLP-1 utilization across Canadian provinces highlights a massive consumer shift. Estimated Canadian Adult GLP-1 Adoption (in Millions) ----------------------------------------------------------------- 2023 |█████████ 1.2M
2024 |███████████████ 1.9M
2025 |█████████████████████ 2.6M
2026 |████████████████████████████ 3.0M+ (Projected peak baseline) -----------------------------------------------------------------
Government Regulation, Restrictions, and Access Controls
Health Canada and provincial ministries maintain strict oversight over how these medications are distributed, prescribed, and subsidized:
Strict Indication Boundaries: While off-label prescribing by physicians has been widespread, Health Canada maintains distinct approvals. For instance, while Wegovy is officially indicated for chronic weight management (in individuals with a BMI ≥ 30, or ≥ 27 with weight-related comorbidities), others like Mounjaro remain officially restricted to Type 2 diabetes indications, creating complex insurance hurdles.
Supply Vulnerability and Shortages: Due to unprecedented global demand, Health Canada’s drug shortages database has frequently listed GLP-1 products under strain. Regulators have continuously cracked down on unverified compounded alternatives, restricting compounding pharmacies unless strict national shortage criteria are met.
Public Formulary Restrictions: Provincial healthcare plans (such as Ontario Drug Benefit or RAMQ in Quebec) maintain rigorous listing criteria. Most provincial public plans restrict full reimbursement strictly to patients with documented Type 2 diabetes who have failed first-line therapies like metformin, leaving cosmetic or primary obesity management dependent on private corporate insurance or out-of-pocket spending.
Health and science reporter. Public health policy, research, and the systems behind them.
Comments (0)
Comments are turned off for this story.